Choosing a mortgage broker: questions for your first call
By Circle37 · Updated · Original guide sources checked 18 October 2026
Before choosing a local mortgage broker, establish who you are dealing with, what their service covers and how they are paid. Ask each firm the same questions and request written answers about scope and fees before deciding whether to proceed.
This guide provides general information to help you compare services. Advice from an appropriately authorised adviser considers your circumstances and whether a particular mortgage is suitable for you.
1. Check the firm behind the conversation
Ask for the firm's legal name, any trading name and its FCA firm reference number. Follow the FCA's guidance on avoiding clone firms to check authorisation, permission for the service offered and whether the contact details match those you have been given. A reference number alone is insufficient: the FCA warns that fraudsters can copy genuine firms' details.
The Financial Services Register guidance also explains appointed representatives. These carry out activities on behalf of a principal firm. If that arrangement applies, ask which principal is responsible and seek confirmation from the principal if the permitted service is unclear.
A directory listing or a review of a broker's website does not verify FCA permissions or establish suitability.
2. Ask what the broker will actually compare
Start with: “Which lenders and types of mortgage will you consider for my enquiry, and what falls outside your service?” Then ask whether the comparison includes deals available only by approaching a lender directly.
The FCA's initial disclosure rules address product-range limitations and disclosure where direct deals are excluded. A broad description of market access still needs a practical explanation of what the firm will consider for you.
Explain whether your enquiry concerns a purchase, remortgage or rental property. Ask whether the firm offers advice for that type of enquiry and who will provide it. If your enquiry concerns a rental property, ask the adviser to explain which services they offer for that situation.
3. Separate fees, payment timing and commission
Ask for a written explanation of any broker fee, how it is calculated, when it becomes payable and whether any refund conditions apply. Also ask whether the firm receives lender or other third-party commission, and whether that affects the fee you pay.
Use the firm's written fee and commission explanation to compare costs. If something is unclear, ask the adviser to explain it before you agree to proceed.
Make the questions concrete: “What would I owe if I stopped before an application, if the lender declined it, or if the purchase fell through?” These are questions to resolve with the firm, rather than assumptions about its terms. Ask which costs the broker's explanation covers and which would be charged separately by others.
4. Clarify who does the work and how you will communicate
An office nearby may be convenient, but check the working arrangements as well. Ask whether appointments are in person, by telephone or by video, and whether the same adviser remains involved throughout.
Useful questions include who checks documents, who follows up with the lender, how updates are provided and who handles questions when the adviser is away. Request the complaints procedure and ask the firm to explain any applicable external complaint route.
You can begin a shortlist using the local mortgage broker directory. When reading an individual entry, such as the Active Mortgage & Insurance Solutions listing, use it to frame questions about the service you need. Confirm current scope directly and complete the FCA checks separately.
5. Use the same question sheet for each call
Copy this table into your notes and add a column for each firm. Record unanswered points explicitly so they remain visible when you compare replies.
| Question to ask | What to record |
|---|---|
| What legal entity provides the service, and under what FCA arrangement? | Firm name, reference number and any principal |
| Will you give advice for my type of enquiry? | Named adviser and service boundaries |
| What lenders or products are outside your comparison? | Exclusions, including direct-only deals |
| What could I pay, and at which stage? | Fee basis, payment triggers and refund terms |
| Do you receive commission, and does it offset my fee? | Written explanation of the arrangement |
| Who handles documents, updates and complaints? | Responsibilities and agreed contact route |
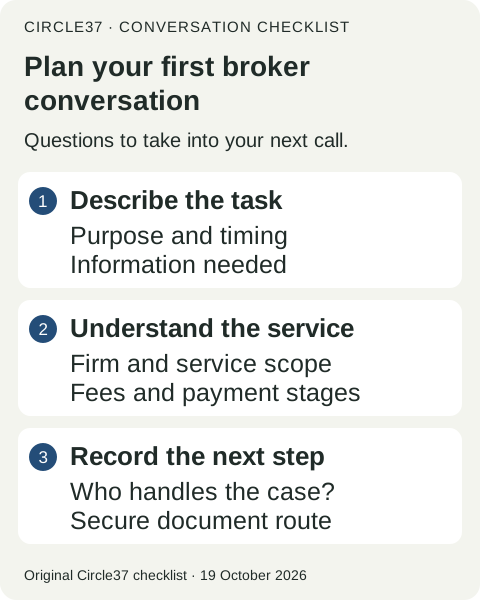
Before calling, prepare a short summary of your purpose, property location, employment or income pattern and any deadline you want to discuss. Ask what documents are needed and how to share them securely. After the call, request clarification of missing answers before agreeing to the next step.